Predictions of AI-driven monopoly have outpaced the evidence. Several years into the generative AI boom, regulators have investigated, firms have invested, and markets have shifted—yet durable market power and demonstrable competitive harm remain elusive.
More than a year ago, Dirk Auer and I challenged the “hyperbolic and dystopian” narrative dominating discussions about competition in artificial-intelligence (AI) markets. We argued that concerns about competition risks—and calls for tougher enforcement—were unwarranted or overstated. AI markets were, in general, highly competitive. More importantly, the AI revolution offered an opportunity to revisit some of the assumptions driving competition concerns in digital services, including data as a barrier to entry and the role of network effects.
AI markets continue to evolve at breakneck speed. This makes it useful to revisit recent developments through the lens of economic and legal principles that inform competition policy. This post is the first in a biweekly series tracking those developments.
Rather than chase the news cycle, I will focus on concrete changes across the AI stack—compute, models, data, integration, and governance. The aim is to reassess, and where necessary push back on, common claims about competition, concentration, and market power. Over time, the series will examine infrastructure investment, talent mobility, model development, new products and services, partnership dynamics, and regulatory responses.
The goal is to connect real-world developments to the competition-policy and enforcement debate, and to test maximalist claims about inevitable concentration or competitive harm against observed market evidence.
The guiding question remains straightforward: Has the AI industry evolved toward monopolistic control of key inputs or demonstrable harm to competition, or toward layered, dynamic competition?
A Lot of Scrutiny, Little Evidence of Harm
A striking feature of the AI competition-policy landscape is the gap between enforcement activity and outcomes. Agencies have devoted significant resources to AI cases, yet have issued few decisions finding anticompetitive conduct or reduced competition. This is especially true of partnerships between incumbent firms and AI startups, which have drawn sustained scrutiny. Despite this, policymakers often acknowledge—at least implicitly—that AI markets remain competitive, even if popular media accounts suggest otherwise.
Over the past two years, competition authorities on both sides of the Atlantic have repeatedly raised concerns about AI partnerships and investments. In January 2025, the Federal Trade Commission (FTC) published a staff report summarizing preliminary findings from an inquiry launched a year earlier. The report examined “relationships between the world’s current largest Cloud Service Providers (‘CSPs’) and two of the most prominent AI model developers” and identified three “areas to watch going forward”:
- The partnerships could affect access to key inputs, such as computing resources and engineering talent.
- The partnerships could increase contractual and technical switching costs for AI developers.
- The partnerships could give CSPs access to sensitive technical and business information unavailable to rivals.
The report, however, offered no concrete evidence of competitive harm in generative AI markets. It did not find that these partnerships created dominant positions or even that dominance was a likely outcome. In his concurring and dissenting statement, then-Commissioner and now-FTC Chair Andrew Ferguson underscored the point:
[T]he limited, brief nature of the study should foreclose the drawing of broad conclusions about the AI industry and its future, or even about the partnerships themselves. The staff report acknowledges as much, deploying hedging language throughout Section 5 and making clear that “an analysis of the impact that these partnerships might have on competition is beyond the scope of this report.” The Commission therefore should not have published speculation about what the future may hold. Readers should skip Section 5 of the Report, or read it with tremendous skepticism.
The UK Competition and Markets Authority (CMA) has taken a similarly cautious approach after investigating multiple AI partnerships, including Microsoft’s deals with Mistral AI, Inflection AI, and OpenAI, as well as Amazon’s partnership with Anthropic.
The CMA cleared the Microsoft-Mistral AI deal in May 2024. It found that Microsoft’s potential shareholding—less than 1%—did not confer influence over Mistral’s policy or board. The agreement’s compute and distribution commitments were also unlikely to create dependency sufficient to affect Mistral’s commercial strategy.
The CMA also cleared Microsoft’s “acquihire” of Inflection in September 2024. It concluded the transaction would not substantially lessen competition in either consumer chatbots or foundational models, citing Inflection’s small market share and early-stage models. That same month, the CMA cleared Amazon’s $4 billion investment in Anthropic, finding that Anthropic UK did not meet the relevant turnover threshold.
Following a 15-month pre-notification investigation, the CMA concluded in March 2025 that the Microsoft-OpenAI partnership did not give rise to a relevant merger situation. It found no “change of control by Microsoft from material influence to de facto control over OpenAI.”
The European Commission has reached similar conclusions. It reviewed NVIDIA’s acquisition of Run:ai and cleared the deal unconditionally in December 2024, after a referral from Italy’s competition authority under its call-in powers. Although the Commission found that “NVIDIA likely held a dominant position in the global market for discrete GPUs for use in datacentres,” it also found that Run:ai lacked a significant position in “GPU orchestration software.” The transaction therefore raised no competition concerns.
Separately, after an extensive review of the Microsoft-OpenAI partnership, the Commission concluded in June 2024 that Microsoft had not acquired lasting control over OpenAI. The partnership did not qualify as a merger. The Commission continued to assess exclusivity provisions under abuse-of-dominance rules but never opened a formal investigation or brought charges. In any event, those concerns appear to have diminished as the partnership evolved—from cloud-service exclusivity to a right of first refusal.
In Brazil, the Conselho Administrativo de Defesa Econômica (CADE) opened administrative proceedings in mid-2024 to assess whether Amazon, Microsoft, and Google should have notified their AI partnerships. The agency focused on potential gun-jumping under Brazilian law. The investigations—covering Amazon-Anthropic, Microsoft’s arrangements with Mistral AI and Inflection AI, and Google’s deal with Character AI—remain ongoing, but have not produced enforcement actions.
Regulatory scrutiny also extends to conduct-based theories of harm, though these cases remain unresolved. In July 2025, Italy’s competition authority opened proceedings into Meta’s preinstallation of Meta AI within WhatsApp. The authority alleged that Meta abused its “dominant position in the market for consumer communications apps” by placing its AI services in a “prominent position.” According to the agency:
Meta appears capable of channelling its customer base into the emerging market, not through merit-based competition, but by “imposing” the availability of the two distinct services upon users, potentially harming competitors.
It later imposed interim measures, ordering Meta “to immediately suspend the WhatsApp Business Solution Terms in order to preserve access to the WhatsApp platform for Meta AI’s competitors.” CADE and the European Commission have initiated similar actions.
As Giuseppe Colangelo notes in recent International Center for Law & Economics (ICLE) comments to the French competition authority, these theories of harm may not align with market realities. While the cases “resemble longstanding debates over vertical integration and self-preferencing,” he argues that “AI markets remain highly dynamic and characterised by considerable competitive uncertainty. Even if Meta seeks to leverage messaging dominance into AI services, success cannot be presumed.” Even in jurisdictions more inclined to intervene in digital markets, agencies face an uphill battle in proving harm.
The pattern is consistent. After extensive scrutiny, agencies have uncovered no solid evidence of anticompetitive harm. Some investigations remain open, but enforcement outcomes appear unlikely. This does not prove that anticompetitive conduct is absent. Still, given the scale of regulatory effort—and the lack of findings—it is reasonable to infer that such outcomes are, at minimum, unlikely in AI markets.
Schumpeterian Competition in Real Time
Stepping back, the broader picture matters. Since November 2022, the AI industry has seen rapid improvement, shifting market shares, and constant entry. This is high-stakes Schumpeterian competition—not creeping monopolization—and the dynamic is well captured by a now-familiar internet meme:

A brief look back makes the point. When OpenAI launched ChatGPT in November 2022, some predicted “first-mover dominance” of the kind often associated with digital markets. Within two months, ChatGPT reached 100 million users—the fastest adoption of any consumer application on record.
The launch jolted incumbents. Within weeks, Google declared a “code red.” CEO Sundar Pichai reassigned teams and brought back co-founders Larry Page and Sergey Brin for emergency strategy sessions—even though Google had invented the transformer architecture underlying modern large language models (LLMs). The rushed February 2023 launch of Bard, Google’s ChatGPT competitor, produced a factual error in its first demo. A startup had made a tech giant scramble.
Entry and expansion followed quickly. Anthropic released Claude in March 2023, iterating rapidly and positioning itself around safety, long-context processing, and enterprise reliability. By late 2025, it reportedly captured about 40% of enterprise LLM spending, surpassing OpenAI. Elon Musk’s xAI launched Grok in November 2023 and integrated it into X with real-time platform data. Perplexity, founded in August 2022 by former OpenAI, Google, and Meta researchers, grew into an AI search alternative valued at $18 billion by July 2025, handling more than 780 million queries per month.
Google, despite its early stumble, regained ground. Competition around ChatGPT has intensified:
The top chatbot’s market share fell from 69.1% to 45.3% between January 2025 and January 2026 among daily U.S. users of its mobile app. Gemini, in the same time period, rose from 14.7% to 25.1% and Grok rose from 1.6% to 15.2%.
The data, obtained by Big Technology from mobile insights firm Apptopia, indicates the chatbot race has tightened meaningfully over the past year with Google’s surge showing up in the numbers. Overall, the chatbot market increased 152% since last January, according to Apptopia, with ChatGPT exhibiting healthy download growth.
On desktop and mobile web, a similar pattern appears, according to analytics firm Similarweb. Visits to ChatGPT went from 3.8 billion to 5.7 billion between January 2025 and January 2026, a 50% increase, while visits to Gemini went from 267.7 million to 2 billion, a 647% increase. ChatGPT is still far and away the leader in visits, but it has company in the race now.
As of this writing—after the company’s feud with the Department of War—Anthropic’s Claude ranks No. 1 among free iPhone apps on Apple’s App Store. In early February, it ranked 42.
The pace of entry and the volatility of market shares point to low barriers to entry and intense competition. Google’s experience underscores the point. Despite access to Search, YouTube, Android, and Chrome—data advantages some viewed as insurmountable—it took more than a year to catch up to a well-funded startup. When it did, it competed on the merits: better models (Gemini 3 Flash, Nano Banana) and improved distribution (AI Overviews), not exclusionary use of data.
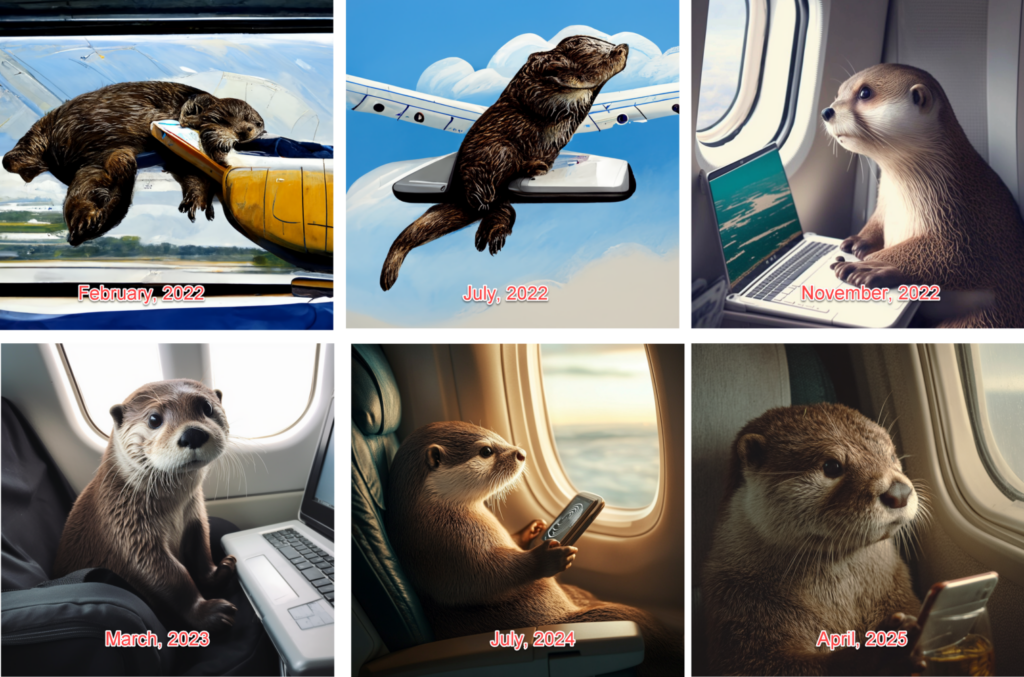
Model performance has also improved at an unprecedented pace. Ethan Mollick’s “Otter test”—asking image models to generate an otter on a plane using Wi-Fi—illustrates the speed of progress.
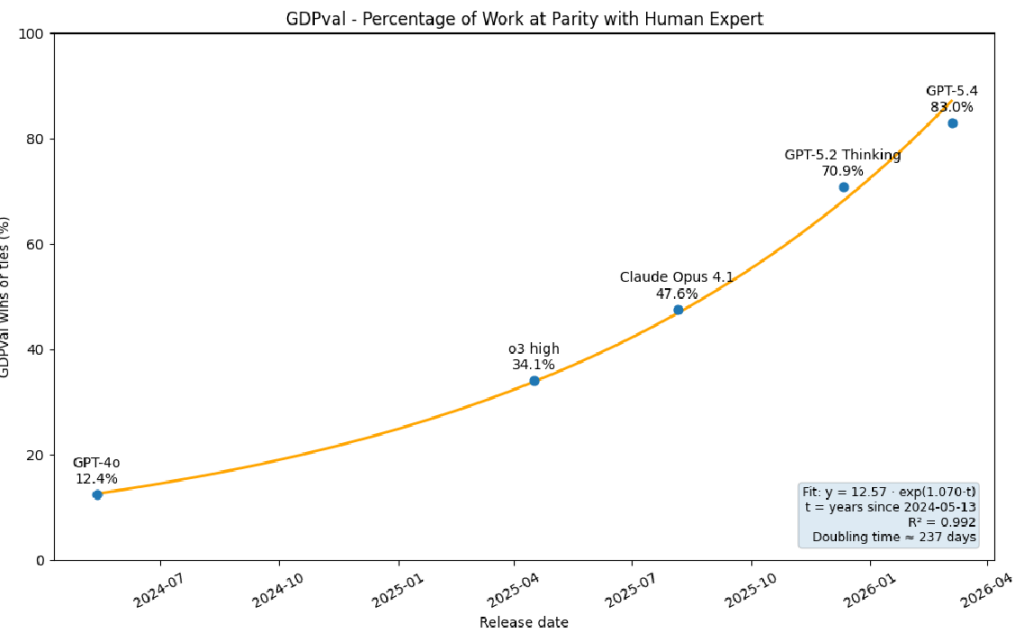
He also points to benchmarks such as GDPval, where industry experts compare AI and human performance on complex tasks. Leading models now match or exceed top-tier human practitioners 82% of the time.
Competition has also come from unexpected quarters. In January 2025, DeepSeek—a Chinese startup founded in 2023—released its R1 reasoning model. It matched or exceeded OpenAI’s o1 model at a fraction of the training cost (about $6 million). As RAND observed, this “demonstrates that the barrier to entry is low enough that new entrants can be competitive,” making it “too soon to pick winners and losers.” Even allowing for uncertainty around DeepSeek’s reported costs, its emergence suggests that early leaders will struggle to build durable moats or enjoy the “quiet life” of a monopolist.
Open-source models reinforce this conclusion. Meta’s Llama family, Mistral’s models, and a wave of Chinese open-weight releases have enabled thousands of developers to build competitive applications without massive proprietary infrastructure.
Low switching costs further intensify competition. Jason Furman, former chairman of the Council of Economic Advisers, recently noted in The New York Times that switching costs have “forced companies to pass the gains from innovation on to users.” In his words:
There are no lazy monopolists in the A.I. space coasting on past advantages. Over the past year, the top spot on the Arena leaderboard has moved among those three companies, with strong performances from newer arrivals such as the Chinese company DeepSeek and the French firm Mistral — many of which require far less capital than earlier generations of A.I. companies.
Moreover, no single company dominates across A.I. areas. Anthropic currently leads in text and coding, OpenAI in text-to-image generation, xAI (founded three years ago) in image to video and Google in search-integrated A.I.
This assessment is notable coming from Furman, who co-authored the “Unlocking Digital Competition” report for the United Kingdom’s Treasury—a report often associated with a “winner-take-most” view of digital markets. As he acknowledges, many expected AI to reinforce those dynamics. So far, it has not.
Competition has also driven sharp price declines. Inference costs have fallen dramatically since late 2022. OpenAI’s most capable model at the time cost $20 per million tokens. GPT-4o-mini now delivers better performance for $0.15-$0.60 per million tokens—a reduction of more than 97%. Research from Epoch AI finds that the cost of achieving GPT-4-level performance has fallen roughly 40x per year, or about 70% annual deflation.
This discussion has focused on consumer-facing markets, where entry and market-share volatility are most visible. But similar dynamics appear across the AI stack. At the infrastructure layer, concerns about graphics processing unit (GPU) concentration and cloud dependencies may carry more weight. NVIDIA’s position in AI accelerators, for example, raises potential input-foreclosure questions that do not arise in chatbot markets—although Google’s tensor processing units (TPUs) and Amazon’s Trainium chips provide meaningful competition.
Data advantages may also matter more in specialized domains, such as medical imaging or legal research, than in general-purpose models. Future posts will examine each layer—compute, cloud infrastructure, training data, and applications—to assess whether apparent concentration translates into durable market power, or whether competitive dynamics resemble those observed in consumer-facing markets.
The Dystopia That Didn’t Arrive
In short, the dystopian narrative—that data-driven network effects would create insurmountable moats, that partnerships would foreclose competition, that big tech would inevitably dominate—has not materialized.
Even so, as of August 2025, some were continuing to call on policymakers to “break up Big AI.” Those calls sit uneasily with the reality of AI markets: dynamic competition, sustained entry, rapid innovation, significant infrastructure investment, and shifting market shares.
None of this rules out anticompetitive conduct. Firms can engage in exclusionary behavior, and when they do, enforcement agencies should act. But that is a far cry from claims that concentration and competitive harm are inevitable.