In “Production, Information Costs, and Economic Organization,” Armen Alchian and Harold Demsetz ask when joint production works better inside a firm than across markets, and what form that firm takes. Their answers turn on a measurement problem: When people produce together, total output doesn’t reveal what each person contributed. Measuring individual contributions is costly, and a firm may handle that cost better than market contracts do.
From this information cost, the paper derives the firm’s legal structure, including ownership, employment, and the line between employee and contractor. This post summarizes Alchian and Demsetz’s paper and offers some thoughts on its contribution to the literature and its weaknesses.
A Firm Grip on Shirking
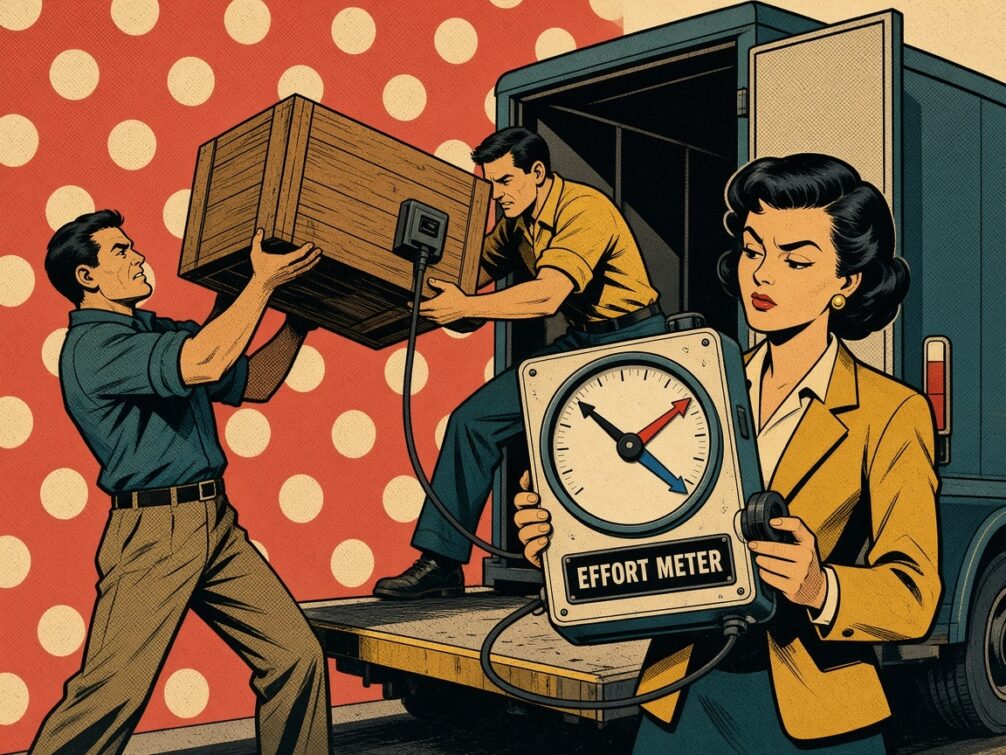
The paper’s central example is simple: “Two men jointly lift heavy cargo into trucks. Solely by observing the total weight loaded per day, it is impossible to determine each person’s marginal productivity” (p. 779). Marginal productivity is the extra output that one input—a worker, for example—adds. In team production, that contribution depends on what the others do. A lifter adds little if the partner doesn’t lift. The day’s total therefore cannot reveal each person’s contribution. Economists call such output nonseparable.
Team production invites shirking. A worker who slacks off keeps all the extra leisure but bears only part of the lost output, because the team shares the shortfall. In the paper’s phrase, “viable shirking is the result” (p. 781).
The remedy is to monitor inputs, but monitoring is costly. Alchian and Demsetz call this the metering problem. Their solution is a specialist monitor. To give her a reason to watch closely, the team gives her “title to the net earnings of the team, net of payments to other inputs” (p. 782). She becomes the residual claimant, keeping whatever remains after paying the others. Every bit of shirking she prevents adds to her income.
The paper then defines the firm by five rights the monitor holds: She claims the residual earnings, observes how inputs behave, and serves as the common party to every input’s contract. She can also change the team’s membership and can sell the whole position. That bundle, Alchian and Demsetz argue, is what it means to own a classical firm. Ownership, in this view, solves a measurement problem.
From Coase’s Insight to Testable Predictions
The paper is partly a response to Ronald Coase’s theory of the firm. Coase argued that a firm takes on an activity when organizing it internally costs less than buying it on the market. Alchian and Demsetz say their “view of the firm is not necessarily inconsistent with Coase’s,” but call his claim “a difficult proposition to disagree with or to refute” (p. 783). The fact that a firm brought an activity in-house becomes the basis for inferring that the market alternative cost more. But Coase offers no empirical test to support that inference.
Alchian and Demsetz do offer predictions. Professional and artistic work, where effort is hard to observe, should take place in small partnerships whose members monitor each other. Profit sharing should appear in small teams, where a specialist monitor costs more than she saves. In corporations, where stockholders delegate monitoring to managers, rival management teams should keep managers in check through proxy fights—contests for shareholder votes—and takeovers. Some of these predictions are qualitative rather than numerical, and none is easy to test cleanly. But evidence can prove them wrong.
Alchian and Demsetz’s achievement is easy to underrate because it succeeded. Explaining the firm’s boundary—which activities it handles internally—rather than assuming it is now close to standard practice. Standard ideas look obvious in hindsight, but this one wasn’t obvious in 1972.
The paper had to show that the question was worth asking, supply a mechanism specific enough to generate predictions, and use that mechanism to explain the firm’s legal form. That combination explains why the paper became a classic.
Seminal though it is, the paper has shortcomings. Curiously, Alchian and Demsetz seem to have recognized many of them without addressing them.
Why Employers Aren’t Just Customers
Alchian and Demsetz deny that the firm rests on authority. A firm “has no power of fiat, no authority, no disciplinary action any different in the slightest degree from ordinary market contracting between any two people” (p. 777). An employer’s power over an employee is “exactly the same as one little consumer’s power to manage and assign his grocer to various tasks” (p. 777). In their analogy, the employer is the customer, and the employee is the grocer. Either may walk away, so neither commands the other.
The metering argument doesn’t need this claim. Team production and costly monitoring could generate the firm’s bundle of rights whether or not the employer also holds authority. The denial reads as an unnecessary defense of classical price theory—the traditional account of how prices coordinate market activity. The paper’s core contribution survives without it.
The claim also sits uneasily with employment law, which distinguishes employees from independent contractors. Courts have held employers liable for employees’ torts. Employees owe duties of loyalty to their employers, and states may enforce agreements that restrict employees from working for competitors. A grocer’s relationship with customers has no clear counterpart to any of these.
An equal right to exit also doesn’t mean equal stakes in exit. A grocer sells to many customers, so losing one costs a small share of revenue. A typical employee sells labor to one buyer, so losing that buyer costs all of it. A grocer may attract a replacement customer with little effort, while a worker may face a long and costly job search. Jobs differ in ways that customers buying bread don’t.
Loss aversion compounds the asymmetry: People tend to weigh a loss more heavily than an equal gain. Because the worker stands to lose more than the employer, she may accept less favorable terms than she otherwise would.
The analogy also presumes that a worker has many potential employers. In “Labor Market Power,” David Berger, Kyle Herkenhoff, and Simon Mongey estimate a model of local labor markets dominated by relatively few employers and find economically significant distortions. Where employers have such power, wages fall below the value of workers’ added output for reasons unrelated to metering.
Alchian and Demsetz acknowledge market power. Asking why sports teams own athletes’ future services, they name “cartelization and monopsony gains to team owners”—gains from coordinating their behavior or limiting athletes’ options—as well as “costs of monitoring production of athletes.” They then concede, “we know not on which to rely” (p. 793, n. 16).
That’s a candid admission that they cannot distinguish between competing explanations. Monitoring costs and market power produce similar arrangements, and the paper cannot tell them apart. Its opening denial of an employer’s power is hard to square with that admission.
The Monitor’s Conflicting Incentives
Alchian and Demsetz raise the obvious objection to their own solution: “who will monitor the monitor?” (p. 782). Their answer is the residual claim. A monitor who keeps what remains after paying the inputs gains from monitoring well.
But the monitor also gains from paying less. The residual is output minus payments, so understating a worker’s marginal product—the extra output she contributes—directly raises the monitor’s income. The problem follows from the model’s own premise: Individual contributions are hard to observe, which is why the firm exists. For the same reason, workers can’t check the monitor’s valuations. The information gap that justifies a central monitor may also bias her judgments.
The paper names one check, then qualifies it: “[O]ne constraint on the monitor is the aforesaid market competition offered by other monitors, but for reasons already given, that is not perfectly effective” (p. 782). The analysis doesn’t explore what happens when that check falls short. The firm exists because markets cannot cheaply measure what each input contributes. Relying on competition among monitors seems to ask the market to supply the very information the theory says it lacks.
The paper’s treatment of unions shows that Alchian and Demsetz recognize the general problem. Employees monitor employers, too. Wages are “extremely easy to check” (p. 790), but contingent pay—compensation that depends on future conditions, such as pensions—isn’t. Employees therefore hire a specialist, the union agent. That agent, the paper notes, “has incentives to use pension and retirement funds not entirely for the benefit of employees” (p. 790). The same reasoning applies to the residual claimant, but the paper doesn’t extend it there.
When the Work Is Part of the Pay
The model’s workers trade leisure against income and shirk when shirking is hard to detect. Otherwise, they’re identical: Each dislikes effort to the same degree.
Alchian and Demsetz recognize that people differ. The firm’s role in judging inputs is “obscured in the theoretical literature by the assumption of homogeneous factors”—the idea that workers and other inputs are alike (p. 793). They also note that personal relationships matter. Partnerships form among relatives and long-standing acquaintances “because each knows better the other’s work characteristics and tendencies to shirk” (p. 790).
These differences matter for shirking, too. If workers differ in their distaste for effort, the firm must sort workers as well as measure their contributions. Offering a range of contracts lets workers choose. If those least averse to effort choose the least supervised terms, that selection does part of monitoring’s job. A model of identical workers cannot generate that response or explain why workers doing the same job at the same firm sign different contracts.
The simplification matters most for nonprofits. No one can sell an ownership stake in a nonprofit, so no one captures the value of improving it through such a sale. The paper concludes that “one should, therefore, find greater shirking in nonprofit, mutually owned enterprises” (p. 790).
That’s plausible. If nonprofit pay runs below private-sector pay, the paper can explain the gap as compensation in kind: Workers accept less money in exchange for other benefits. Pay may be “lower in pecuniary terms and higher in leisure, conveniences, and ease of work” (p. 781).
Volunteers are harder to explain. A volunteer receives no pay and still supplies effort. If withholding effort were the only nonmonetary reward from work, volunteering would be shirking with nothing to shirk from. Volunteers get something from making an effort, and the model has no term for that.
Paid nonprofit work may be an intermediate case: part wage labor and part donated effort. Lower nonprofit pay then has two explanations. Workers may shirk more easily, as Alchian and Demsetz suppose, or accept less because they value what the work produces. Both stories predict the same wage gap.
The model’s gap traces to one simplifying assumption. Footnote 5 says that “leisure stands for all nonpecuniary income for simplicity of exposition” (p. 780). But the shirking mechanism requires nonmonetary rewards to fall as effort rises. When those rewards rise with effort instead, the incentive runs the other way. Such workers may supply more effort than their wages alone would buy.
Alchian and Demsetz consider a nearby idea and set it aside. Team spirit and loyalty improve a team, they argue, “because of the reduced shirking—not because of some other feature inherent in loyalty or spirit as such” (p. 790). That keeps motivation within the framework as a check on shirking. But it doesn’t account for a worker for whom the work itself is part of the pay. Such a worker needs no deterrent to shirking.
Noisy Signals and Lasting Relationships
The behavioral signals the paper relies on are noisy. Clues to productivity come from watching inputs, such as “how rapidly does a man move to the next piece to be loaded, how many cigarette breaks does he take” (p. 780). A long break could signal shirking or recovery from hard work. Imperfect measurement is the paper’s premise, so this doesn’t undermine the argument. But the less reliable the signal, the wider the monitor’s unchecked discretion and the costlier monitoring becomes.
The paper also sets aside the effects of repeated dealings within employment. Footnote 2 treats reputation as an asset worth the future income it secures, but applies the idea to market exchange in general. The paper denies that employment rests on long-term contracts “any more than on a series of short-term or indefinite length contracts” (p. 784).
Jobs likely last longer than one-off purchases. If they do, repeated dealings—and the incentive to preserve a valuable relationship—may do some of the work the paper assigns to the residual claimant.
Why the Model Still Matters
Alchian and Demsetz’s central insight holds up. Individual contributions are costly to observe, joint production makes them costlier still, and firms may exist partly to manage that difficulty. By tying how people produce together to how firms organize, the paper moved the study of firms toward testable predictions.
The limitations raised here mostly concern what the model leaves out: the unequal stakes of separation for employer and employee, the monitor’s incentive to undervalue contributions only she can observe, and differences in workers’ distaste for effort. The paper’s explicit prediction about nonprofits seems to me the least likely to survive a more realistic model.
The paper remains a classic. Many later papers build on it, and some address the limitations noted here. Its contribution lies less in getting every part right than in advancing the economic study of firms.
It’s also worth reading today. New technologies can track workers’ keystrokes and deliveries, changing the cost of observing individual contributions and possibly the firm’s role. More than 50 years later, Alchian and Demsetz’s questions and analysis remain relevant.
Further Reading
- Armen A. Alchian & Harold Demsetz, “Production, Information Costs, and Economic Organization,” American Economic Review, Vol. 62, No. 5 (1972).
- R. H. Coase, “The Nature of the Firm,” Economica, Vol. 4, No. 16 (1937).
- David W. Berger, Kyle F. Herkenhoff & Simon Mongey, “Labor Market Power,” American Economic Review, Vol. 112, No. 4 (2022).