Showing archive for: “Financial Regulation”
A Fee Too Far: Merchants, Surcharges, and the War on Plastic
Earlier this summer, my family took a vacation to Ocean City, Maryland, where the boardwalk offered ice cream, souvenirs, and an unexpected lesson in payment economics. Every retailer we visited added a surcharge of at least 3% for credit-card payments, yet not one posted a sign. I discovered the charges only later, while checking my ... A Fee Too Far: Merchants, Surcharges, and the War on Plastic
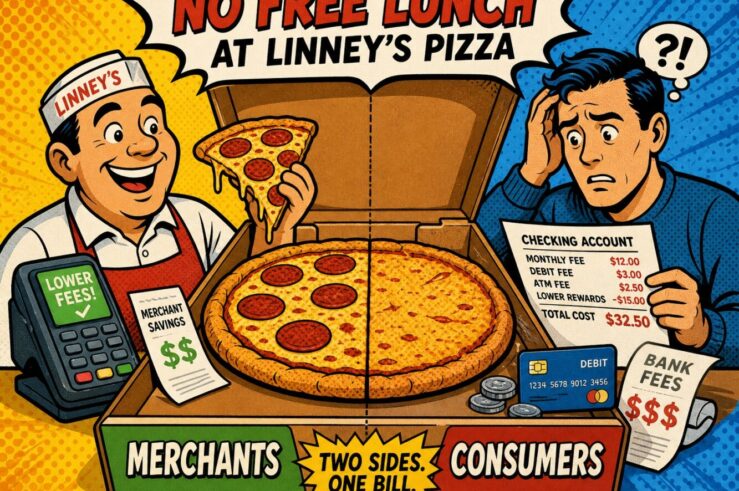
No Free Lunch at Linney’s Pizza
A pizza shop wants lower debit-card fees. Fair enough. But if it wins, the tab may not land where diners expect. It could reshape administrative law, narrow the Federal Reserve’s discretion, and make ordinary checking accounts more expensive. That is what is at stake in Linney’s Pizza, LLC v. Board of Governors of the Federal ... No Free Lunch at Linney’s Pizza
Merger Control or Political Tool? Lessons from Spain’s Attempt to Stall the Sabadell Merger
The Spanish government has approved BBVA’s hostile takeover bid for Banco Sabadell but as I anticipated in an earlier Truth on the Market post, it did so while imposing stringent conditions. Both banks will be required to maintain separate legal identities, management, and operations for at least three years, potentially extendable to five. These conditions ... Merger Control or Political Tool? Lessons from Spain’s Attempt to Stall the Sabadell Merger
When Theoretical Rigor Misses Reality: Why Interchange-Fee Caps Won’t Benefit Consumers
Interchange fees charged by payment networks have in recent years been one of the most heated and persistent battles in financial regulation. These fees—typically 1-3% of credit-card transaction value in the United States—are charges that banks impose on merchants for processing credit- and debit-card transactions. What started as an obscure technical detail has exploded into ... When Theoretical Rigor Misses Reality: Why Interchange-Fee Caps Won’t Benefit Consumers
How Spain Is Politely Killing a Bank Merger
Rather than moving to formally block Banco Bilbao Vizcaya Argentaria’s (BBVA) proposed acquisition of Banco Sabadell, the Spanish government is signaling that it is prepared to attach such a broad set of conditions—justified in vague terms as serving the “public interest”—that the deal would likely collapse under its own weight. It’s a kind of regulatory ... How Spain Is Politely Killing a Bank Merger

Capital One/Discover Deal: Rumored Concerns Lack Substance
The proposed merger of Capital One Financial Corp. and Discover Financial Services Inc. would appear to be moving toward completion, as more than 99% of the companies’ shareholders voted last month to approve the $35.3 billion deal. According to at least one report, however, anonymous sources in the U.S. Justice Department (DOJ) suggest the agency ... Capital One/Discover Deal: Rumored Concerns Lack Substance

CFPB’s Overdraft Fee Price Controls Would Be Counterproductive
The Consumer Financial Protection Bureau (CFPB) announced a final rule last week to impose price controls and onerous disclosure rules on overdraft fees charged by those banks and credit unions with assets of more than $10 billion. At first glance, such interventions might seem like a win for consumers, particularly those with low incomes who ... CFPB’s Overdraft Fee Price Controls Would Be Counterproductive
Capital Confusion at the New York Times
In a recent guest essay for The New York Times, Aaron Klein of the Brookings Institution claims that the merger between Capital One and Discover would “keep intact the broken and predatory system in which credit card companies profit handsomely by rewarding our richest Americans and advantaging the biggest corporations.” That’s quite an indictment! Fortunately, Klein also ... Capital Confusion at the New York Times
The FT Misunderstands the Economics of Credit-Card Markets
In a recent piece for the Financial Times, Brendan Greeley argues that the misnamed Credit Card Competition Act would reduce inflation. In it, Greeley recycles numerous myths about the nature of credit-card markets that have long been rebutted by serious economic research. Both theory and ample evidence from the United States and other countries shows ... The FT Misunderstands the Economics of Credit-Card Markets
The Paradoxical Perils of Mandatory ‘Competition’ in Merchant Routing of Credit-Card Transactions
Sen. Richard Durbin (D-Ill.) earlier this month introduced legislation that aims to manufacture competition in the routing of credit-card transactions. If enacted, the measure would require that merchants be able to choose from at least two networks when processing most credit-card transactions. While this would result in competition over routing, it would harm other forms ... The Paradoxical Perils of Mandatory ‘Competition’ in Merchant Routing of Credit-Card Transactions
Four Horsemen of the Bureaucratic Apocalypse Come for AI
Four prominent horsemen of the Biden administration’s bureaucratic apocalypse—the Federal Trade Commission (FTC), U.S. Justice Department (DOJ) Civil Rights Division (DOJ), Consumer Financial Protection Bureau (CFPB), and the U.S. Equal Employment Opportunity Commission (EEOC)—came together April 25 to issue a joint statement pledging vigorous enforcement against illegal activity perpetrated through the use of artificial intelligence ... Four Horsemen of the Bureaucratic Apocalypse Come for AI
Is Pix Really the End of Credit Cards?
In late August, Roberto Campos Neto, the head of Brazil’s central bank, is reported to have said about Pix, the bank’s two-year-old real-time-payments (RTP) system, that it “eliminates the need to have a credit card. I think that credit cards will cease to exist at some point soon.” Wow! Sounds amazing. A new system that ... Is Pix Really the End of Credit Cards?