

Adam Smith warned that people in the same trade rarely meet without the conversation turning to a scheme to raise prices. Antitrust enforcers on both sides of the Atlantic now suspect they can skip the meeting—a shared shareholder may do the job.
In May 2025, the U.S. Justice Department (DOJ) and Federal Trade Commission (FTC) backed a lawsuit alleging that BlackRock, Vanguard, and State Street used their stakes in competing coal companies to coordinate output cuts. The following month, the European Commission fined Delivery Hero and Glovo for participating in a cartel facilitated by Delivery Hero’s minority stake in Glovo.
Testing whether ownership links foster collusion is tricky. Cartels are illegal, so researchers usually see only those that get caught. Those may look little like the ones that escape detection.
A recent working paper by Vincent Abraham, Florian Ederer, and Catarina Marvao sidesteps that problem with data from Sweden, where cartels remained legal until 1993. Firms had to disclose cartel agreements when authorities requested them. Failure to register carried penalties that included fines or up to six months’ imprisonment. The authors matched that registry with ownership records for publicly listed Swedish companies from 1985 to 1993.
Their key measure, a “profit weight,” captures how much a firm treats a rival’s profits as its own because they share owners or one holds shares in the other.
The Stockholm Stock Club
Abraham and his co-authors found that firms that gave more weight to a rival’s profits were more likely to belong to a cartel. The effect was modest. An increase of one standard deviation—a common measure of variation in the data—in the profit weight corresponded to a 0.44 percentage-point increase in the probability of cartel membership, from 7.64% to 8.08%.
That relationship ran in only one direction. Ownership ties predicted cartel membership for the firm that gave weight to its rival’s profits, but not for the rival itself. Both firms belonged to the same cartel in only about 0.1% of the firm-pair observations, leaving too few cases to draw firm conclusions. As the authors note, their model “is silent on which firms collude with which.”
A 2001 study of American farm cartels offers a possible answer.
One Firm Holds the Umbrella
Darren Filson, Edward Keen, Thomas Borcherding, and I studied federal marketing orders—legal cartels that let fruit, nut, and vegetable growers restrict the quantity and quality of produce reaching the fresh market. Of 182 crop-and-state combinations, only about a third ever maintained an order for at least three consecutive years.
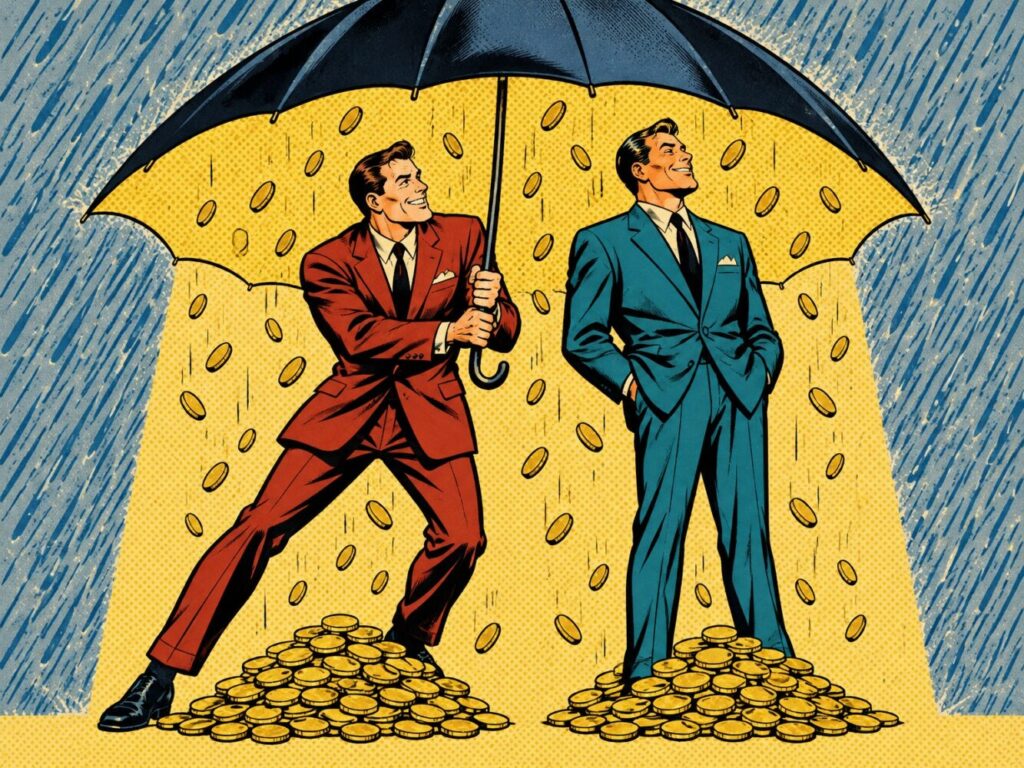
We treated each cartel as a dominant seller competing with a “fringe” of smaller producers outside the agreement. When the cartel restricts supply, prices rise for everyone. Outsiders enjoy the higher price without limiting their own sales. In 1942, the United Date Growers of California complained that its members “grumble at holding the umbrella” for growers who stayed out.
Common ownership changes that arithmetic. If a cartel member and an outsider share owners, those shareholders collect part of the outsider’s windfall. That could help explain why ownership ties predict one firm’s cartel membership but not its rival’s.
The Swedish study’s authors don’t draw that connection, but their model points in the same direction. A firm’s gain from joining a cartel grows with the weight it gives to the profits of any rival that benefits from the cartel. An outsider selling at the cartel’s higher price fits the bill.
We also found that cartels were far more likely to form where a large cooperative—a business owned by its grower-members—already existed. A 20-percentage-point increase in the largest cooperative’s market share raised the probability of adopting a marketing order by about 19 percentage points. These cooperatives also exercised direct control. They voted on their members’ behalf and enforced quality standards.
A Stake Is No Steering Wheel
Abraham and his co-authors found a similar contrast between control and passive investment when they separated profit weights by source. Ownership by other listed companies—including direct stakes in rivals—showed a stronger link to cartel membership. Passive common ownership—in which funds, families, or other investors hold stakes in both firms—showed a smaller, less consistent relationship. It also corresponded to a lower likelihood that the rival belonged to a cartel. That fits the umbrella story. A rival with shared owners can stay outside the cartel and still collect the higher price.
Swedish ownership also looked different from its American counterpart. Groups such as the Wallenberg family often controlled firms through layers of holding companies and shares with extra voting rights. As the authors acknowledge, concentrated control may strengthen the link between ownership and coordination compared with markets where ownership is more dispersed.
The study thus supports close scrutiny of direct stakes between rivals, as in the Delivery Hero case. It offers much less support for the theory behind the lawsuit against BlackRock, Vanguard, and State Street.
A central question remains. The ownership links existed before the firms joined cartels, consistent with the idea that shared owners helped pave the way for collusion. But it also fits a simpler explanation: Investors who anticipated a profitable cartel may have bought shares before it formed.
Distinguishing those explanations requires ownership changes unrelated to cartels. Suppose a bank merger transferred a block of shares to a new owner for reasons unrelated to collusion. If firms that suddenly shared that owner then joined cartels more often, that would strengthen the case that ownership helped cause collusion. If they didn’t, the evidence would offer less support for that explanation and leave open the possibility that investors were simply anticipating cartel profits.
For now, the Swedish findings echo what American farm cartels suggested 25 years ago. Collusion comes more easily when owners have a hand in running competing firms. Simply holding shares in both appears to matter less.
A shared shareholder is one thing. A hand on both steering wheels is quite another.